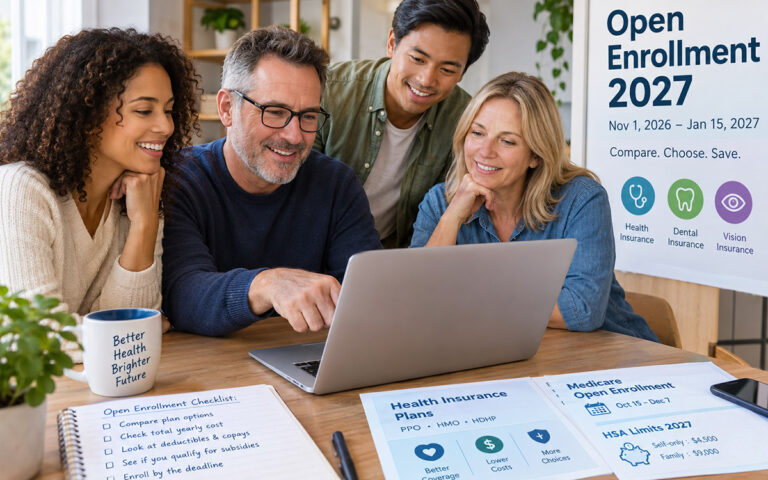
Open enrollment for 2027 runs from November 1, 2026, to January 15, 2027, on HealthCare.gov, with a December 15 deadline for January 1 coverage. Enhanced ACA subsidies expired at the end of 2025 and have not been renewed, so many enrollees face higher costs. Medicare open enrollment runs October 15 to December 7. HSA limits for 2027 are $4,500 self-only and $9,000 family. Compare plans based on total yearly cost, not just premiums.
Picture this: an email lands with the subject line “Your 2027 benefits elections are due.” You open it, see three plans with names like Gold PPO and HDHP Plus, and immediately want to click “keep my current plan” and move on. Most people do exactly that. It feels safe. But during open enrollment in 2027, that habit could cost you hundreds or even thousands of dollars.
Premiums are climbing again, federal subsidy rules have changed, and many plans are reshuffling deductibles and drug coverage. Whether you buy coverage on the ACA marketplace, get it through work, or are on Medicare, the plan that fit last year may not fit next year.
This guide walks through the dates you cannot miss, what happened to the enhanced premium subsidies, and a simple way to compare plans on what you will actually pay. You will also see the 2027 HSA and FSA limits, which are some of the easiest ways to stretch your healthcare budget.
Open Enrollment 2027 Dates You Need to Know
Quick take: On HealthCare.gov, open enrollment 2027 runs November 1, 2026, through January 15, 2027. Enroll by December 15 if you want coverage to start January 1.
HealthCare.gov’s dates and deadlines page confirms the November 1 to January 15 window. A 2025 federal rule would have shortened it to end December 15, but a federal court blocked that provision in June 2026, and CMS confirmed in August that the traditional schedule stays.
The key dates in one place:
- October 15 to December 7, 2026: Medicare open enrollment
- November 1, 2026: ACA marketplace open enrollment begins
- December 15, 2026: Last day to enroll on HealthCare.gov for January 1 coverage
- January 15, 2027: HealthCare.gov open enrollment ends (coverage starts February 1)
- Employer plans: Usually a two- to four-week window in October or November, set by your employer
States that run their exchanges set their own deadlines. According to Healthcare Insider’s state roundup, California, New Jersey, New York, Rhode Island, and D.C. run through January 31, 2027, while Idaho closes December 15. Always confirm on your state’s marketplace site.
What Happened to the Enhanced ACA Premium Subsidies?
Quick take: The enhanced premium tax credits expired on December 31, 2025, and as of October 2026 Congress has not brought them back. For 2027, the older, less generous subsidy rules apply, including the income cap at 400% of the federal poverty level.
The enhanced credits started in 2021 and were later extended through 2025. They lowered premiums for most enrollees and removed the income ceiling on help. ASTHO’s legislative timeline notes the House passed a three-year extension on January 8, 2026, but the Senate never followed. A bipartisan Senate compromise has been discussed, yet nothing has become law.
What that means for 2027 shoppers:
- Income cap is back: The Commonwealth Fund notes that individuals earning above $63,840, or families of four at $132,000 or more, get no premium help
- Premiums keep rising: Insurers proposed a median 15% increase for 2027, after benchmark premiums jumped more than 20% in 2026
- Bigger repayment risk: Starting with tax year 2026, Benefit Champs reports that excess advance credits must be repaid in full, so report income changes promptly
- More paperwork: New income verification rules mean you should have pay stubs or tax records ready
If Congress acts later, rules could change mid-season. Be sure to check HealthCare.gov for updates before you finalize.
“The plan that fit last year may be the most expensive choice this year.”
How to Pick a Plan That Saves You Money
Quick take: Compare plans on total yearly cost: premiums plus the deductible and copays you realistically expect. The lowest premium is not always the cheapest plan.
A plan with a $250 monthly premium and a $7,000 deductible can cost far more than a $400 plan with a $1,500 deductible if you have regular medical needs. On the other hand, if you rarely see a doctor, the lower premium might win. The only way to know is to do the math.
A simple four-step comparison:
- Step 1: Add up 12 months of premiums for each plan.
- Step 2: Estimate your medical use: doctor visits, prescriptions, and any planned procedures.
- Step 3: Add expected out-of-pocket costs, using the out-of-pocket maximum as a worst-case scenario.
- Step 4: Confirm that each plan’s network and drug list covers your doctors, hospitals, and medications.
Keep in mind that the 2027 ACA out-of-pocket maximum rises to $12,000 for individuals and $24,000 for families, per the Benefit Champs summary. That ceiling is your worst-case exposure in a challenging year. Make sure your emergency fund could handle it, or lean toward a plan with lower cost sharing.
Making the Most of Employer Open Enrollment
Quick take: Employer plans usually beat marketplace plans on price because your employer pays part of the premium. Use your enrollment window to review every option, not just health insurance.
Your employer’s open enrollment window is often short, sometimes just two weeks. If you miss it, you generally cannot change plans until next year unless you have a qualifying life event like marriage or a new baby.
Smart moves during workplace open enrollment:
- Read the change summary. Look for new premiums, deductibles, and network changes.
- Check spouse coverage. Some employers add a surcharge if your spouse has access to their plan.
- Review dental, vision, and life insurance. These small premiums add up across a year.
- Update your 401(k) rate. Many employers bundle retirement elections with open enrollment.
- Know the affordability test. For 2027, employer coverage counts as affordable if employee-only premiums stay at or below 10.22% of household income, which usually rules out marketplace subsidies.
If your employer coverage fails that test, you may qualify for marketplace help instead. A quick call to HR can clarify where you stand.
“Run the numbers on total yearly cost, not the monthly premium alone.”
Medicare Open Enrollment: October 15 to December 7
Quick take: Medicare open enrollment runs October 15 to December 7, 2026, for coverage starting January 1, 2027. Use it to switch Medicare Advantage or Part D drug plans if your current one no longer fits.
Medicare plans change their premiums, networks, and covered drugs every year. Your plan should send you an Annual Notice of Change by early fall. Read it, because a drug moving to a higher price tier can quietly raise your costs.
What to review this season:
- Part D drug cap: The annual out-of-pocket limit for covered drugs rises to $2,400 in 2027, up from $2,100, according to Humana’s Part D overview
- Part B premium: The 2026 Medicare Trustees Report projected $209.50 a month for 2027, up from $202.90. CMS is expected to announce the official figure in the fall
- Networks: Confirm your doctors are still in network for Medicare Advantage plans
- Plan Finder: Use Medicare.gov’s plan comparison tool with your actual prescriptions entered
Retirees are also getting a 3.6% Social Security raise for 2027. Comparing Medicare plans this fall could protect more of that raise than any other single step.
2027 HSA and FSA Limits for Open Enrollment
Quick take: For 2027, you can put up to $4,500 into an HSA with self-only coverage or $9,000 with family coverage. The health FSA limit is projected to rise to $3,500, with the official IRS figure expected this fall.
Health savings accounts and flexible spending accounts both let you pay medical costs with pre-tax dollars. That can trim your effective cost of care by 20% to 30% or more, depending on your tax bracket.
Key 2027 numbers:
- HSA self-only: $4,500 (official, per IRS figures reported by 401k specialist)
- HSA family: $9,000 (official)
- HSA catch-up (55+): $1,000
- Health FSA: $3,500 projected, up from $3,400 (Marsh projection)
- FSA carryover: $700 projected, if your plan allows it
A bigger change: bronze and catastrophic marketplace plans now count as HSA-eligible under the 2025 reconciliation law, per Benefit Champs. That opens HSAs to more marketplace shoppers. HSA money never expires and can be invested, making it a strong addition to long-term savings strategies. FSA money, by contrast, is mostly use-it-or-lose-it, so estimate your expenses carefully.
Common Open Enrollment Mistakes to Avoid
Quick take: The costliest mistakes are auto-renewing without checking, ignoring drug coverage, and underestimating out-of-pocket risk. A 30-minute review can prevent all three.
Most open enrollment errors come from rushing. With subsidy rules and premiums shifting for 2027, a quick review matters more than usual.
Watch out for these:
- Auto-renewing blindly. Your plan’s price, network, or drug list may have changed.
- Skipping the subsidy check. Update your income on HealthCare.gov so your tax credit is accurate.
- Forgetting new insurer exits. Benefit Champs reports nine carriers are leaving the marketplace for 2027, so some enrollees must choose a new plan.
- Overfunding an FSA. Any leftover money above the carryover is forfeited.
- Missing the deadline. Set calendar reminders for December 7 and December 15.
If your situation is complicated, a licensed insurance navigator or a qualified financial professional can help you weigh your options.
Conclusion: Your Open Enrollment 2027 Checklist
Open enrollment 2027 rewards people who take a fresh look. Key takeaways:
- Mark your dates. Medicare closes December 7, and HealthCare.gov needs your choice by December 15 for January 1 coverage.
- Expect less subsidy help. Enhanced credits expired, so shop carefully and update your income.
- Use tax-advantaged accounts. HSA limits are $4,500 and $9,000, and FSAs are projected at $3,500.
Want to make smarter money decisions with more confidence? Explore more practical guides from Dollar Thinking for clear insights on investing, personal finance, business, debt management, and long-term wealth building. For more practical financial insights, visit Dollar Thinking’s savings guides to explore helpful guides on investing, business finance, debt management, saving money, and building stronger financial habits.
Frequently Asked Questions
When is open enrollment for 2027 health insurance?
On HealthCare.gov, open enrollment for 2027 coverage runs November 1, 2026 through January 15, 2027. You must enroll by December 15, 2026, for coverage starting January 1. State-run exchanges may have different deadlines, some extending to January 31.
Are the enhanced ACA subsidies available in 2027?
No, current law prohibits it. The enhanced premium tax credits expired December 31, 2025, and Congress has not passed an extension as of October 2026. The original rules apply, so households above 400% of the federal poverty level generally get no premium help.
When is Medicare open enrollment for 2027?
Medicare open enrollment runs October 15 through December 7, 2026. Changes you make take effect January 1, 2027. You can switch Medicare Advantage plans, change Part D drug plans, or return to Original Medicare during this window.
What are the 2027 HSA contribution limits?
For 2027, the HSA limit is $4,500 for self-only coverage and $9,000 for family coverage. People 55 and older can add $1,000. You must be enrolled in an HSA-eligible high-deductible health plan to contribute.
How do I choose the best health insurance plan during open enrollment?
Compare plans on total yearly cost, combining premiums with your expected deductible, copays, and coinsurance. Check that your doctors and medications are covered. Use the out-of-pocket maximum to judge your worst-case cost in a high-use year.